Ddr3 Server Ram Memory
Overview
Product sourcing insights & recommendations
The DDR3 server RAM market in 2026 is experiencing a structural shortage driven by a massive reallocation of wafer capacity toward AI-centric HBM and DDR5 production. As major manufacturers like Samsung and SK Hynix stand firm on their End-of-Life (EOL) schedules, supply for legacy DDR3 has reached a bottleneck, causing a "catch-up price rally" and lead times extending to 30–40+ weeks.
I have compiled a detailed market insight report below, covering:
- Pricing Surges: 55-60% QoQ contract price jumps in early 2026.
- Supply Risks: The transition from Tier-1 manufacturers to specialty makers like Nanya and ESMT.
- Enterprise Demand: The surge in sourcing legacy modules to maintain aging infrastructure.
- Pricing Benchmarks: Current wholesale rates for ECC Registered (REG) modules.
Here is the market report for DDR3 server RAM. You can proceed with:
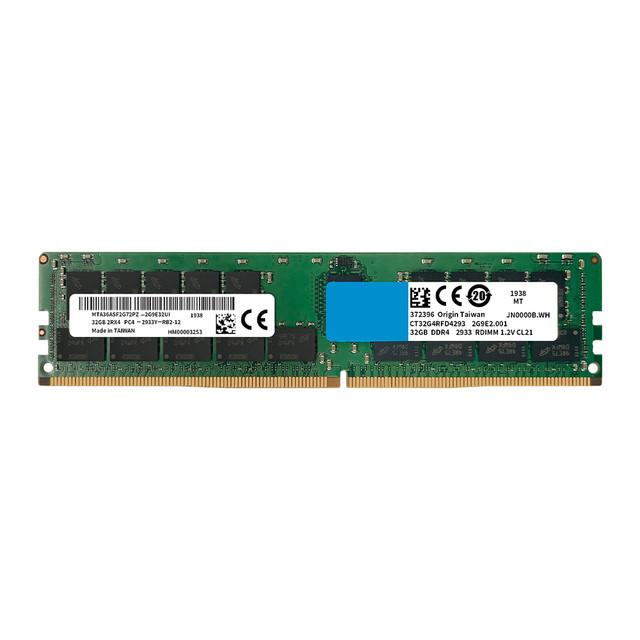
Ddr3 Server Ram 8gb 16gb Ecc Reg Wholesale
Products · 2 lists
Deep Dive · Full Report
Full Market Report
1 document · Live-fetched from source
Related Searches
Explore more sourcing topics & related categories
Sources & References
19 sources cited · Verified industry data & reports
Supply Chain Brief: Market Conditions in 2026 | VersaLogic
www.versalogic.com
For example, TrendForce notes that contract prices “solidified gains” (with DDR5 leading) in early March[1]. Reuters reports TrendForce now forecasts a 90–95% quarter-on-quarter jump in first-quarter 2026 DRAM prices, driven by the AI boom[2]. In the spot market, recent data show DDR4 prices basically flat (a slight 0.3% dip) as Samsung temporarily froze DDR4 quotes[3], but overall prices remain at record highs across DDR3/DDR4/DDR5. Supply & Lead Times All DRAM categories are under strict allocation. For legacy memory, reports indicate that heavy enterprise buying of DDR4 has simultaneously tightened DDR3 supply, causing high-density DDR3 products to become scarce[4]. Even though some buyers are chasing DDR3 to save cost, factory capacity is limited and order fill rates are low. Recent industry reports confirm that memory makers are prioritizing high-end (AI/server) products, leaving legacy DDR4/DDR3 supply scarce. Lead times are very long, and customers should plan accordingly. DRAM pricing has remained on an upward trajectory and availability is still constrained, reinforcing the need to align near-term demand with timely order placements. Pricing Trends Contract DRAM prices have continued to firm. Industry analysts note that major cloud providers (Google, Microsoft, Amazon, Meta, etc.) have placed open-ended DRAM orders, essentially agreeing to take “as much supply as available”[6]. Memory suppliers are therefore concentrating wafer starts on server DDR and high-bandwidth (HBM) products[1][6]. This leaves conventional PC/embedded DRAM in tighter supply, indirectly driving up costs for DDR4/DDR3 further. Near-Term Outlook Little relief is expected in 2026. New fab capacity is coming—but not soon. Memory experts stress that announced expansions (Samsung, SK Hynix, Micron, Kioxia, et One of our key supply partners recently advised customers to plan for potential DRAM price increases of 10–20% per month through the end of 2026. While actual market movements may vary, this guidance reflects the level of concern that continues to exist within the supply chain regarding future availability and replacement costs. Supply Constraints Continue Across DDR3, DDR4, and DDR5 Availability remains constrained across all major DRAM families. DDR3 continues to be impacted by limited legacy manufacturing capacity, making long-term supply commitments increasingly difficult to secure.
When Will Server RAM Prices Drop? March 2026 Update
www.bacloud.com
Server DRAM prices have soared into 2026 and show no sign of falling soon. After years of relative stability, late 2025 saw a “RAMpocalypse”: high-capacity DDR5 modules jumped 2–4× in price within months. For example, a 64 GB high-end DDR5 kit that cost a few hundred dollars in mid-2025 was over $800–900 by year’s end. In industry words, “this is not a normal boom-bust cycle but a structural reallocation of capacity”. The final DDR4 phase-out adds pressure, too: older DDR4 chips are being discontinued, making legacy modules unexpectedly scarce (and in some cases more expensive than DDR5). Builders forced to migrate to DDR5 have further amplified demand for it. Outcome: With demand far exceeding available chips, memory suppliers have pricing power. They are raising contract prices aggressively. For example, TrendForce recently forecast a 90–95% increase in DRAM contract prices in Q1 2026 compared with Q4 2025. TrendForce data (via Reuters) shows Q1 2026 up by almost 90–95%, and even in mid-2026, suppliers warn of ongoing hikes (e.g., +60% in Q1 alone). Analysts say DDR5 pricing “won’t return to normal in 2026”. That said, some stabilization may occur in late 2026. New fabrication capacity is on the way: Samsung’s P4 fab and SK Hynix’s M15X are slated to ramp up DRAM output through 2026. If AI demand doesn’t accelerate further, these fabs could finally narrow the supply gap. Gartner warns that PC BOM costs could jump by ~23% in 2026, nearly wiping out sub-$500 PCs. Cisco and HP have signaled similar price hikes on enterprise gear. Even items that use older memory (automobiles, TVs, appliances) are affected because manufacturers have reduced production of legacy DRAM.
[News] DDR4 Reportedly Leads Legacy Memory Rally with Q1 Prices ...
www.trendforce.com
Commercial Times reports that DDR4, DDR3, NOR flash, and SLC/MLC NAND are entering a fresh supply-demand reversal. Among the mature products, the report adds that heading into 2026, enterprise buyers have become more aggressive in sourcing DDR4, triggering a sharp first-quarter price jump of up to 50%, with momentum expected to carry into the second quarter. Several major memory makers are preparing to exit DDR4 in 2026, with Samsung reportedly standing firm on its end-of-life schedule. Thus, fresh DDR4 and DDR3 supply is tightening, with demand staying solid across systems, industrial and networking equipment, and parts of data center infrastructure, Commercial Times reports. The report adds that as enterprise customers step up DDR4 procurement in 2026, capacity reallocation has further tightened DDR3 supply. Taiwan’s Nanya Technology could emerge as a major beneficiary of this uptrend. Commercial Times notes that the company, set to announce its fourth-quarter earnings this afternoon, could see revenue surpass NT$300 billion in 2026 as DDR4 prices surge, with gross margins potentially reaching 70%.
Server RAM Market Report H2 2026 — The DRAM Squeeze
datacenterdisk.com
Second, the honest window. Our index's trend series began accruing daily history on March 26, 2026 with a small legacy basket, and the tracked catalog grew from 8 to 51 modules in July 2026. The cause is structural and well documented: AI datacenters are estimated to consume roughly 70% of high-end DRAM output in 2026, per an Avnet market brief citing WSJ, IDC and TrendForce research, and the same brief carries TrendForce's Q1 2026 contract forecasts of DRAM prices up 55-60% quarter over quarter. The 2026 numbers sharpened that picture considerably. The Avnet brief's ~70% figure for AI datacenter consumption of high-end DRAM describes an industry where conventional server memory has become the residual claimant on wafer supply. TrendForce's contract-price forecasts relayed in the same brief — DRAM up 55-60% quarter over quarter in Q1 2026, NAND up 33-38% — mark the fastest contract escalation of the shortage so far. AI datacenters are estimated to consume roughly 70% of high-end DRAM output in 2026 (per an Avnet brief citing WSJ/IDC/TrendForce), and manufacturers shifted wafer capacity to HBM, which earns multiples of conventional DDR5 revenue per wafer.
Legacy DDR2 & DDR3 Memory in 2026: Supply & Technical Guide
suntsu.com
Learn the strategic advantages of MCP Memory for your next design. Explore eMCP vs. uMCP, BOM consolidation, and shortage mitigation strategies. As demand shifted towards the DDR3 market, a second group of buyers downgraded their designs to DDR2. This increase in orders stressed an already fragile supply chain, with only a few dedicated semiconductor design firms and specialty foundries still producing these legacy components. This cascade is visible in the data. TrendForce reports that as enterprise buyers grew more aggressive in sourcing DDR4 through early 2026, capacity reallocation further tightened DDR3, with high-density DDR3 parts such as 2Gb already in acute shortage and a catch-up price rally taking shape [3]. In 2026, the global semiconductor market is experiencing a subtle yet disruptive structural change. While the media prominently highlights next-generation architectures and generative AI, hardware designers and procurement experts working on long-term industrial, networking, and medical platforms encounter a different challenge: a significant shortage in legacy DRAM supply. Standard dynamic random-access memory platforms such as DDR2 and DDR3 continue to be vital for many embedded systems. The lower voltage threshold in SSTL_15 reduces overall power consumption and noise generation, enabling clean signaling at the higher clock speeds required for DDR3’s double-digit gigabyte transfer rates. Navigating the 2026 Memory and NAND Flash Price Surge · DDR4 Market Volatility: How Independent Distributors Ensure Project Continuity
Server DRAM Industry Analysis-3Q26 | TrendForce
www.trendforce.com
Driven by AI Agent computing expansion and third-party outsourcing demand, server shipments and CPU requirements have been revised upward. Memory suppliers face severe capacity constraints due to shifting production toward high-bandwidth memory, driving contract prices up significantly and increasing the share of high-capacity modules.