Mobile Phone S2
Overview
Product sourcing insights & recommendations
The term "mobile phone s2" currently bridges two distinct market narratives in 2026: the launch of the cutting-edge Samsung Galaxy S26 series and a niche but persistent trade in legacy models (original Galaxy S2) and rugged alternatives like the FOSSiBOT S2.
Market Trends & Insights (2026)
The global smartphone market is facing a historic 13.9% year-on-year decline in shipments for 2026, reaching its lowest point in over a decade IdcCounterpointresearch. This downturn is driven by a massive memory crisis (DRAM/NAND shortages), which has caused Bill of Materials (BOM) costs to soar and pushed Average Selling Prices (ASPs) to a record high of $550 IdcIdc.
* Premiumization Surge: While the budget segment ($200 and below) is shrinking rapidly, the premium flagship segment (above $800) remains resilient, dominated by Apple and Samsung IdcCounterpointresearch.
* Segment Shifts: Foldable phones are a rare growth spot, expected to rise by 20% YoY, while legacy 3G/4G budget phones are becoming economically unviable due to rising component costs IdcTechinsights.
Product Analysis: The "S2" Landscape
* Samsung Galaxy S26 Series: Launched in February 2026, this series serves as the market benchmark. The S26 Ultra features a 200MP main camera, a new 50MP 5x periscope lens, and 60W super-fast charging Wikipedia.
* FOSSiBOT S2: A modern alternative in the "S2" naming convention, this rugged device targets the budget-to-mid-tier market with a 50MP camera, 20GB dynamic RAM, and a large 5000mAh battery Google.
* Legacy Galaxy S II: Surprisingly, a retro market persists for the original 2011 Galaxy S2, with units trading between $9.00 and $35.00 for collectors and basic usage GoogleGoogle.
B2B Sourcing Opportunities
Wholesale markets show high activity for "S2-series" keywords, though many listings are for OEM "S25/S26 Ultra" clones that mimic flagship aesthetics at a fraction of the cost ($30–$100) AlibabaAlibaba. Genuine bulk supply for older flagships like the S22+ is available starting at roughly $220/unit for 10+ pieces Alibaba.
Samsung Galaxy S22 S23 S24 S25 Smartphone Bulk Supply
Products · 2 lists
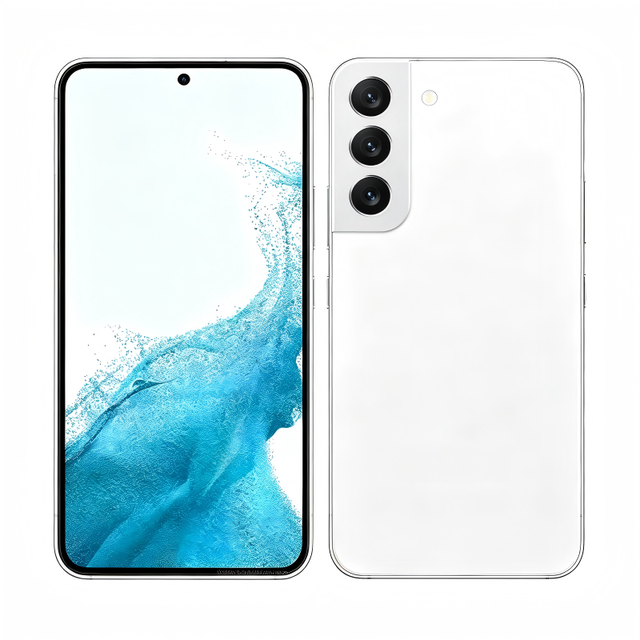
Wholesale Original S22+ Unlocked Smartphone Global Version for Retail and Wholesale Market OEM Supplier
 Shenzhen Century Huitong Technology Co., Ltd.🇨🇳CN8 yrs
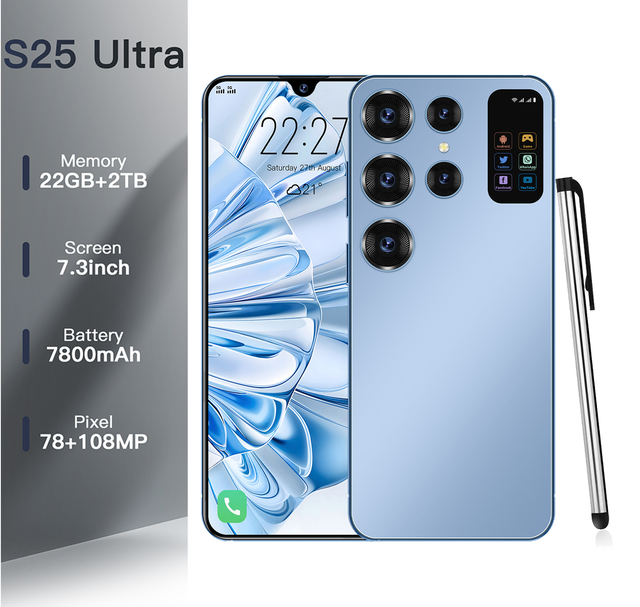
22G+2TB 2026 New S25 ultra Big Screen Global 5G Cell Phones Deca Core CDMA Unlocked 5G Smartphone LTE Cellular Dual-SIM
 Shenzhen Hongyang Tuoyu Technology Co., Ltd.🇨🇳CN1 yr

High Configuration Hot Selling Factory Price S25 Ultra 5G Smartphone 22G+2TB Storage 72MP+108MP Dual Camera Android 15 144Hz LCD
 Shenzhen Shoulder Hong Renju Technology Co., Ltd.🇨🇳CN2 yrs
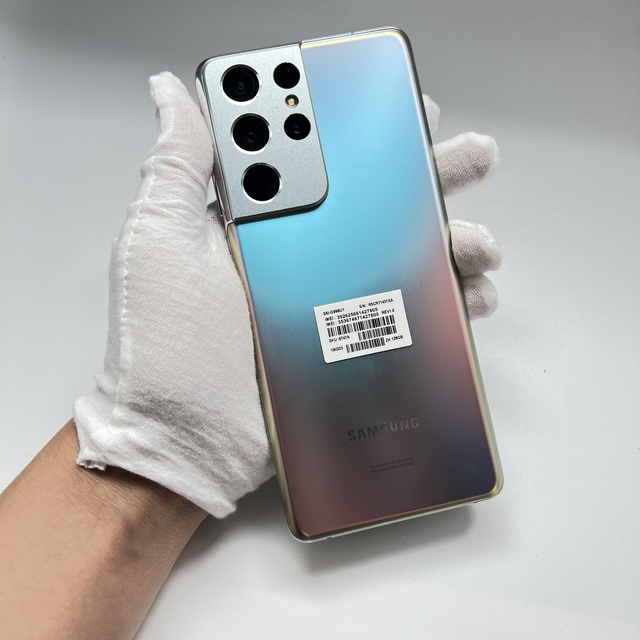
Direct Source Original Bulk Wholesale Used Smartphones Quality Tested Mobile Phones SAM S21 Ultra
 Shenzhen Waley Technology Co., Ltd.🇨🇳CN4 yrs
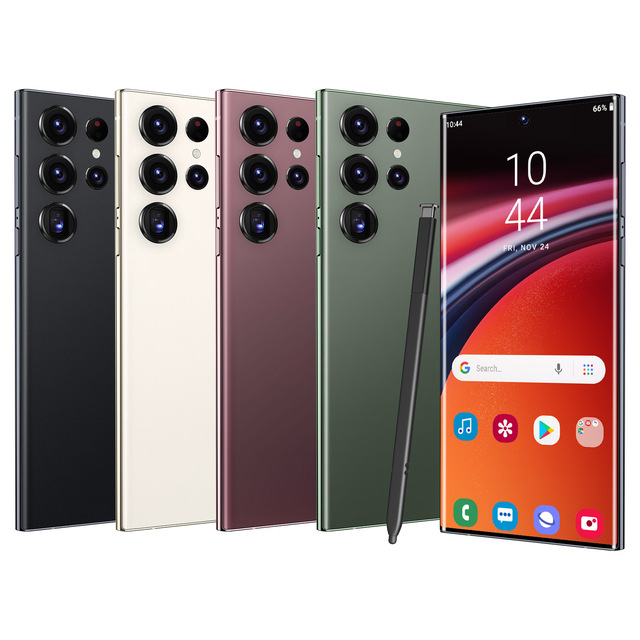
Factory Direct Sale New 6.8" 8-Core 3G+64G Smartphone Mobile Phones S25 Ultra for hot Sale
 STYLE IN MOOD FACTORY COMPANY🇭🇰HK5 yrs
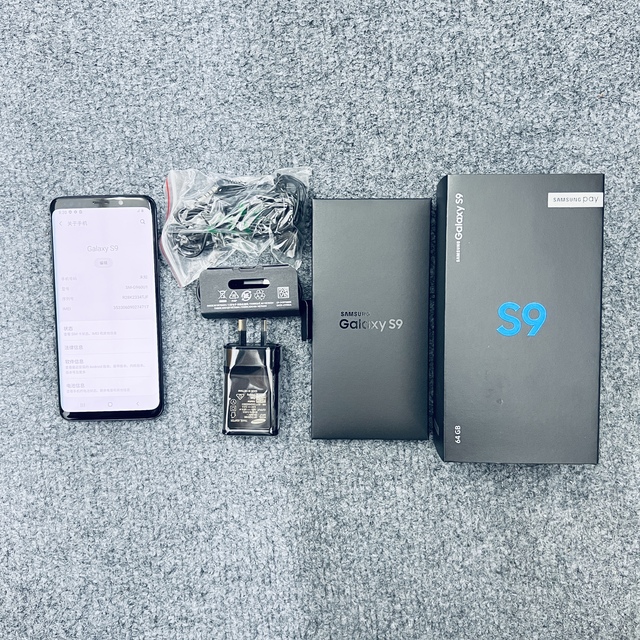
samsung Galaxy S9 Used Phone 64GB Used Phone 4GB RAM Used Phone 3000mAh Used Phone 5.8Inch Used Phone Original
 MIDSUMMER INTERNATIONAL LIMITEDverified🇭🇰HK1 yr
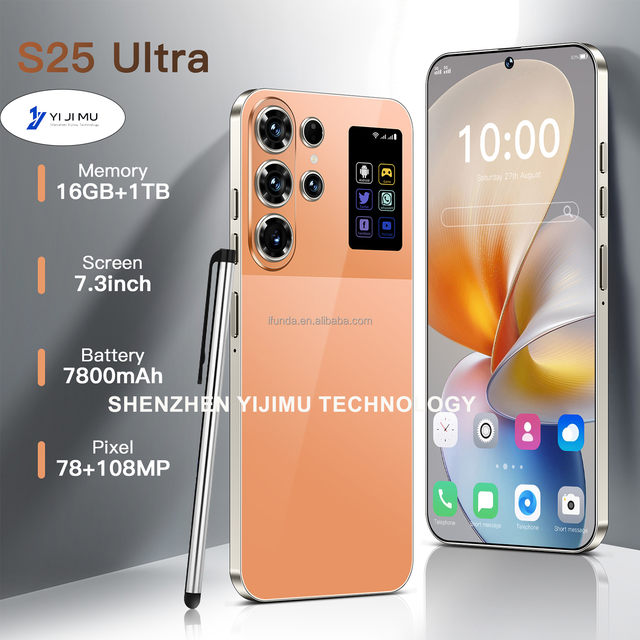
S25 Ultra 16G+1TB Android 15 7.3 Inch LTE Cellular Smartphone Fast Processor Al Scene Recognition Flash Memory Sturdy Durable
 Shenzhen Yijimu Technology Co., Ltd.🇨🇳CN1 yr
2025 New Original Phones S25 ultra Smartphones 5G Dual SIM Cellphone Global Mobile Phone S24 ultra 5g Smartphone Case
 Foshan Yaosheng International Trade Co., Ltd.🇨🇳CN1 yr
2025 S25 Pro 5G Smartphone Unlocked with Big 4K LED Display 108MP Rear Camera 16GB + 1TB Storage Android Mobile Phone Accessory
 Foshan Xusheng Trading Co., Ltd.🇨🇳CN1 yr
S25 Ultra 5G Smartphone 3+64G/4+64G/ 4+128G/8+128G Full Network Android 6.8-Inch 4G Display MTK Processor
S26 Ultra 16GB+1TB 5G 4K ULTRA HD Smartphone 7.3-inch 108MP Camera CDMA LTE Dual Sim Android Unlocked Mobile Phones
S26 Ultra 16GB+1TB 5G 4K ULTRA HD Smartphone 7.3-inch 108MP Camera CDMA LTE Dual Sim Android Unlocked Mobile Phones
Related Searches
Explore more sourcing topics & related categories
Sources & References
17 sources cited · Verified industry data & reports
Global Smartphone Market Share: Quarterly
counterpointresearch.com
• Samsung replaced Apple as the top smartphone player in Q1 2023, driven by its mid-tier A Series and the recently launched S23 series. • Apple’s YoY shipment decline was the least among the top five brands. Consequently, it recorded its highest-ever Q1 share of 21%. • Global smartphone revenues declined by 7% YoY to around $104 billion. Apple, Samsung, Xiaomi increased their Average Selling Prices YoY. Summary · Type: Insight · Published: August 26, 2026 · The global smartphone market declined by 7% YoY in Q2 2026 as the memory shortage deepened and memory prices continue to rise. Xiaomi recorded the steepest decline among the top five smartphone brands, with shipments falling 26% YoY in Q2 2026. The global smartphone market remained under pressure in Q1 2026, with shipments declining 3% YoY driven by the shortage of memory components and weaker demand.
IDC - Smartphone Market Insights
www.idc.com
From here, the winners will be the vendors with the scale and supply leverage to hold demand at prices consumers have never had to pay before.” Francisco Jeronimo, Vice President for Worldwide Client Devices, IDC ... The crisis is not hitting everyone equally. Android bears almost the entire decline, falling 24.3% in 2026 as its most exposed vendors retreat from the entry tiers they can no longer serve profitably. Android share drops seven percentage points in a single year. iOS share does the opposite trend, increasing almost four percentage points from last year to record high 23.6% share as shipments remain relatively resilient, down just 1.3% YoY in 2026. BOSTON, August 28, 2026 – The global smartphone market shrank 7.4 % year-on-year to 276.3 million units in the second quarter of 2026 (2Q26), according to the final historical data from the International Data Corporation (IDC) Worldwide Quarterly Mobile Phone Tracker, The memory crisis continues to disrupt the smartphone market with unprecedented costs and strained supply, with Q2 2026 marking the second quarter of consecutive year-on-year decline. “Memory costs are up nearly 300% from a year ago, and now account for over 65% of BOM at the low end, making survival increasingly difficult for OEMs with low-end portfolios,” said Nabila Popal, senior research director for Worldwide Consumer Devices, IDC. Low-end vendors are doing their best to adjust strategy, cut costs, and shift their portfolios toward higher margin devices; however, the challenge isn’t strategy – it’s creating demand for these traditionally low-end brands at higher price segments. Consumers are increasingly opting for a premium brand when the price gap reduces, and financing is readily available.” · “The second quarter of 2026 brought a widening gap between the top and bottom of the market. The smartphone market has changed character this year. Units are dropping while prices are climbing sharply, with consumers expected to absorb the cost. According to IDC’s Worldwide Quarterly Mobile Phone Tracker, worldwide smartphone shipments will fall 16.7% in 2026 to just over 1 billion units.
SAG: Global Smartphone Shipments Fall 8% in Q2 2026; Samsung and ...
smartanalyticsglobal.com
The divergence between premium and mass-market demand will remain one of the defining industry trends in 2026. Vendors with stronger premium portfolios, broader financing and trade-in ecosystems, and greater flexibility in managing component cost pressures are likely to be better positioned to navigate the ongoing market downturn. ... Unlock expert insights on smartphones, tablets, wearables, and connected devices. Preliminary data from Smart Analytics Global (SAG)’s smartphone 360 series show global smartphone shipments declined 8% year-over-year (YoY) in Q2 2026, broadly aligned with what we forecasted in May. as exchange rate volatility and rising component costs continued to weigh on the market. Continued pressure in affordable and mid-range smartphone segments weighed heavily on overall shipment performance, despite new product launches and ongoing efforts to strengthen the group’s position across selected overseas markets. vivo Group, including iQOO, captured 8% of global smartphone shipments in Q2 2026, down from 9% one year ago. Despite the decline, vivo maintained its position among the world’s top five smartphone vendors and continued to defend its presence across China and several major emerging markets. Among vendors in the “Others” category, Huawei and Nothing stood out with solid shipment performance in Q2 2026.
Q2 2026 Global Smartphone Shipments Slump to Lowest Q2 Level in ...
counterpointresearch.com
Global smartphone shipments fell 11% YoY in Q2 2026 reaching the lowest second-quarter levels since 2013 as the DRAM and NAND shortage intensified. Samsung reclaimed the global leadership position with a 24% market share, recording the strongest YoY growth among the top five brands, as pricing and competitive dynamics in certain regions worked in its favor. Our analyst team, led by seasoned experts, engages with stakeholders across the enterprise – from the C-suite to professionals in strategy, analyst relations (AR), market intelligence (MI), business intelligence (BI), product and marketing – to deliver services spanning market data, industry thought leadership and consulting. Our core areas of coverage include AI, Automotive, Consumer Electronics, Displays, eSIM, IoT, Location Platforms, Macroeconomics, Manufacturing, Networks and Infrastructure, Semiconductors, Smartphones and Wearables. Visit our Insights page to explore our publicly available market data, insights and thought leadership, and to understand our focus, meet our analysts and start a conversation. Global smartphone shipments tumbled 11% YoY in Q2 2026, reaching the lowest second-quarter levels since 2013, according to preliminary estimates from Counterpoint Research's Market Monitor, as the memory shortage deepened and emerged as the dominant drag on the industry. DRAM and NAND prices continued to balloon through the quarter as memory suppliers kept prioritizing AI data center demand over consumer electronics, forcing OEMs to pass rising Bill of Materials (BOM) costs onto consumers via repeated price hikes, particularly on entry and mid-tier devices. This coincided with a broader macro squeeze, slower global growth, higher inflation, and record-low consumer sentiment which hit price-sensitive buyers the hardest." Source: Counterpoint Research’s preliminary Market Monitor report (based on sell-in) Notes: OPPO includes OnePlus and realme. Percentage totals may not add up to 100% due to rounding. Samsung reclaimed its global No.1 position with a 24% share in Q2 2026 and recorded the strongest growth among top five brands.
5 Expectations for the Mobile Market in 2026 | TechInsights
www.techinsights.com
Mobile AI adoption — Google, Apple, and potential disruptors drive consumer traction. Hardware & AI co-evolution — SoCs and DRAM innovation across Android OEMs. Tariffs & trade impact — How pricing and supply chains are being reshaped. Emerging market influence — BRIC nations and new growth regions take the stage. Form-factor innovation — New designs promise to revitalize a stagnating market. Whether you’re a strategist, designer, or executive, this session will equip you with the insights to anticipate change, realign your roadmap, and seize new opportunities. Wayne Lam is the Service Director of Mobile Semiconductors at TechInsights, with over a decade of experience in the consumer electronics and smartphone industries. An expert in mobile technologies, market research, and competitive intelligence, he excels at uncovering insights that help clients understand emerging technologies. The mobile semiconductor market faces an inflection point in 2026. While trade and tariff uncertainties continue to disrupt global supply chains, breakthrough technologies promise to reinvigorate growth in an industry facing maturity pressures.As Google, Apple, and new disruptors expand AI-driven mobile experiences, OEMs are rethinking hardware design, SoC innovation, and DRAM integration to meet rising consumer expectations. As the Director of Device Technologies at TechInsights, Ken Hyers has over 20 years of experience analyzing, forecasting, and advising professionals within the telecommunications industry. He is recognized as an expert in his field, and regularly provides insight for a variety of newspapers, business publications, and wireless trade journals.
Worldwide Smartphone Market to Decline 13.9% in 2026 as Memory ...
www.idc.com
Samsung is expected to grow market share in 2026, defying the broader Android decline by expanding in the premium segment and taking share in the mid-range. A combination of secured memory supply, a stronger Galaxy S26 line-up, and aggressive mid-range positioning is allowing Samsung to capture demand that smaller Android vendors simply cannot serve as memory costs squeeze their bill of materials. Based in London, he leads the research that covers mobile devices, personal computing devices, emerging technologies and the circular economy trends across EMEA. His team delivers data on personal… · Stay ahead in a rapidly evolving market. Get timely insights, trusted research, and actionable guidance to help you make smarter technology and business decisions — whether you’re driving innovation, evaluating solutions, or shaping strategy. Combined, these pressures are compelling vendors to reduce shipments, raise prices and concentrate on higher price tiers — elevating smartphone ASP to a record $550, up $100 from last year. 2026 will be a defining year for the industry as new reality of structurally higher costs take hold. For consumers, it means the era of ultra cheap smartphones is over. The sub-$200 segment, where margins are already thin and consumers are most price-sensitive, will shrink the most. Regions with the highest concentration of sub-$200 devices are facing the sharpest declines: Middle East and Africa (MEA) is forecast to drop 23%, Central and Eastern Europe 19%, and Asia Pacific excluding Japan and China (APeJC) 14%. North America holds up comparatively well, with only a 6.3% decline. The region is dominated by the premium segment, with 60% of shipments in 2026 Q1 above $800, and Apple and Samsung have proven resilient to the crisis at that tier.